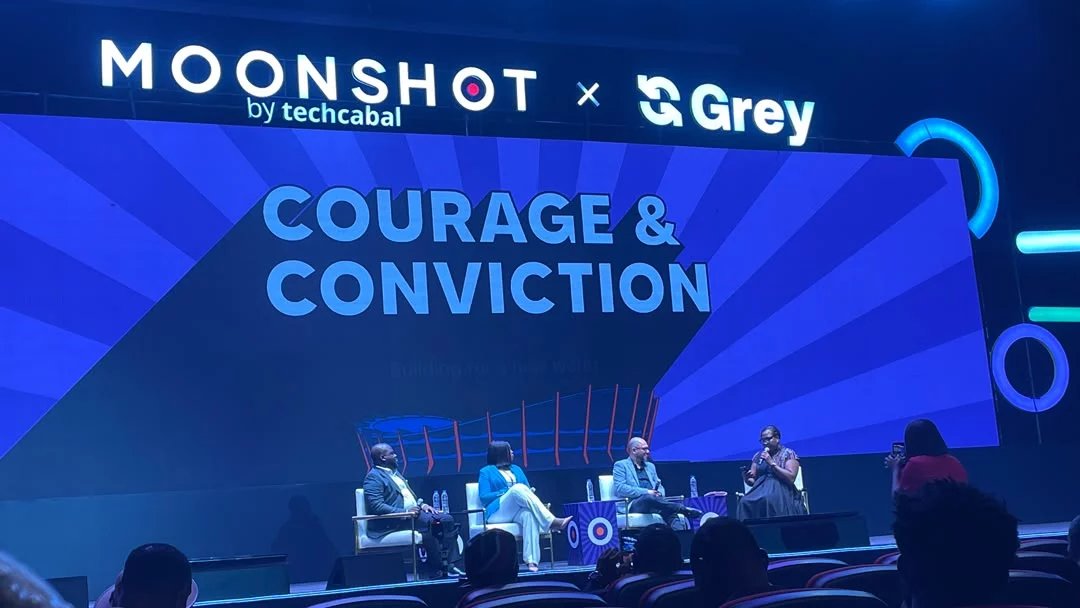
Payment providers must help businesses manage cash flow, understand customers and reduce fraud as accepting digital payments becomes only the first step in adopting technology, fintech executives told Moonshot by TechCabal 2026.
Speaking at a panel titled “The Business Behind the Transaction”, executives from Mastercard, Remita and OPay said merchants needed services that connected payments to their wider operations, alongside reliable support and staff training.
“Let’s understand the customer, let’s solve for the customer problem rather than providing a generic product push across the different businesses,” said Shabir Ahmed, Mastercard’s Senior Vice President for Customer Solutions in Central Africa.
Ahmed identified connectivity, data-driven intelligence and trust as priorities for providers seeking to help businesses operate more effectively. His comments proved that the usefulness of payment technology depends on what businesses can do with it beyond collecting money.
For Remita, that means extending services into financial management, invoicing and statutory compliance, said Abimbola Onyluka, the company’s divisional head for corporate and consumer business.
Businesses need tools that connect their financial information to banks, lenders and regulators, she said. A payment record becomes more useful when it can support borrowing, reporting and decisions about how to manage the business.
But expanding the range of services also requires providers to maintain the reliability of their core payments operations. Onyluka stressed the need for dependable support and the quick resolution of downtime, as payment failures can interrupt sales and affect customer service.
Isimeme Ayobami Owobo, OPay’s director for key account merchants, said businesses that grew faster integrated technology into their operations and trained employees to use it effectively.
Installing a payment terminal was only part of that process, he argued. Merchants also needed to make fuller use of the tools available to them, including QR-code payments that could help speed up transactions.
The discussion highlighted a challenge for payment providers seeking a larger role in merchants’ businesses. Processing a transaction gives them a point of contact with the customer, but turning that relationship into a broader service requires an understanding of how each business operates.
The executives’ argument was that payment acceptance alone offers a limited measure of digital adoption. The greater value comes when businesses can use the information generated by transactions to manage cash, serve customers and plan growth.