In car importing, business owners must find the vehicle and pay the auction house, which could be in another country. This proved harder than expected for Sheriff Adedokun, a serial entrepreneur who founded Clea, a cross-border payments platform for African businesses.
Africa’s fragmented cross-border payments landscape was not new. Businesses trading internationally had relied on banks or other financial intermediaries to move money between markets. By 2022, when Adedokun started importing vehicles from the United States, Nigerian fintechs were building products to make international payments easier. However, the available options did not always work for the transactions he needed.
“I tried to use some of the fintech platforms in Nigeria, but it didn’t work because most of my payments were rejected,” Adedokun told TechCabal in an interview. “Then I had to go to the bank, fill a form, and try to do the transfer. There was also a limit on sending international transfers from Nigerian banks.”
He explained that US vehicle auction platforms required payments to come directly from the person or business buying the car, as third-party transfers could be rejected.
Car importation was one example of a deluge of businesses that had to pay suppliers before their orders could be shipped. Total imports stood at over ₦15 billion ($11.1 million) in the first quarter of 2025, according to National Bureau of Statistics (NBS) data.
In 2024, Adedokun founded Autoclear, a business that helped customers source vehicles and pay US auction platforms. While working with importers, he noticed they also had to pay shipping companies, freight forwarders, and brokers, each with its own payment requirements and separate from the auction houses where they buy the cars.
So, he teamed up with his longtime friend Sidney Egwuatu to build Clea, a cross-border payments platform to serve African businesses importing goods from overseas. The company developed the product in stealth before publicly launching in December 2025.
How Clea moves money across borders
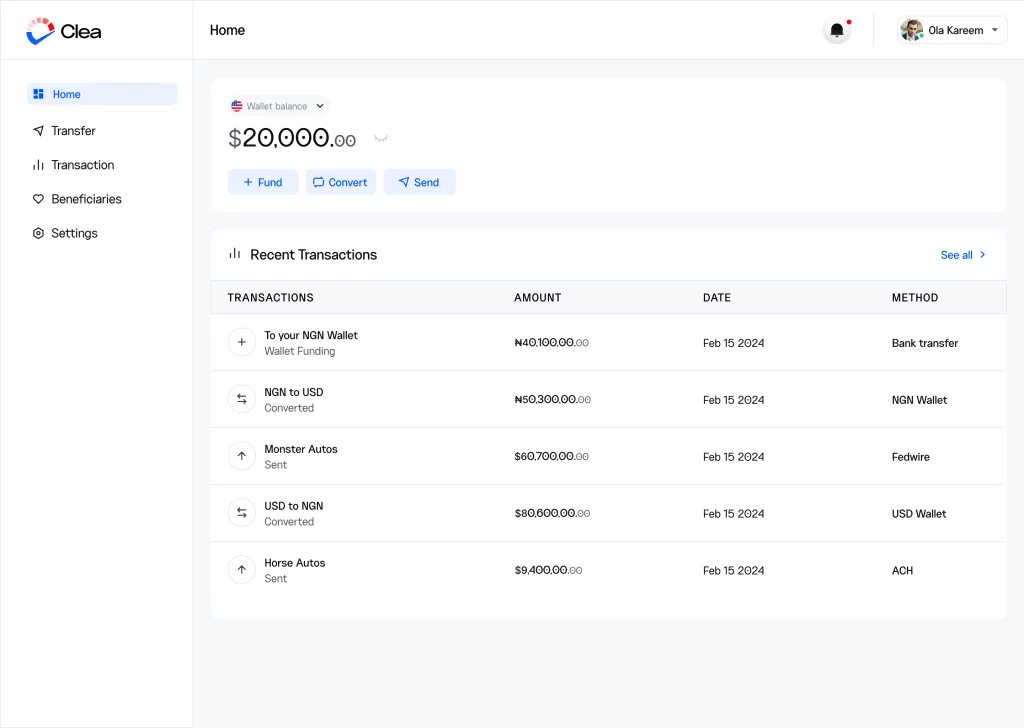
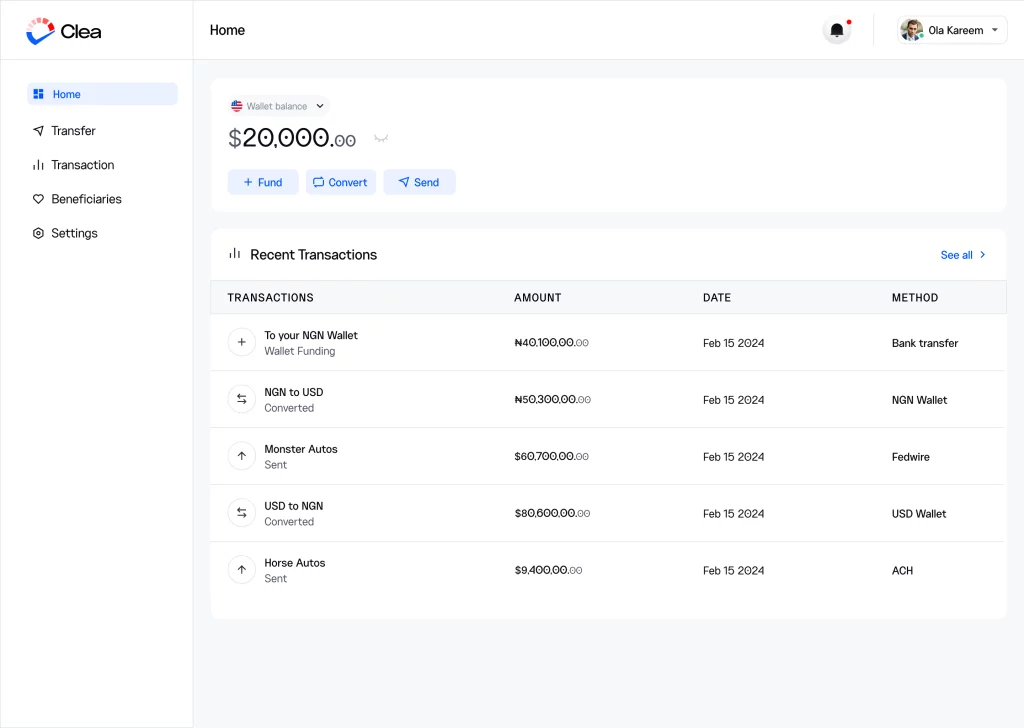
Clea allows businesses to manage international supplier payments from a single platform. After signing up and completing verification, a business can fund its account in naira from a Nigerian bank account, convert the funds into the required currency, and add its overseas supplier as a beneficiary. During a live product demonstration, Adedokun showed that the platform supports currencies including the US dollar, British pound, euro, and Chinese yuan.
To add a new supplier, a customer provides details such as the recipient’s address, country, and the nature of their relationship with the beneficiary. After adding the beneficiary, the customer can initiate a payment using the available payment routes for that destination. Adedokun said payments to US beneficiaries could go through ACH, Fedwire or the Real-Time Payments (RTP) network, while payments to other destinations could be routed through SWIFT.
Stablecoins form part of the infrastructure Clea uses to move value between the different parts of this payment process. Adedokun said the platform is designed to keep this complexity out of sight, allowing customers to focus on funding their accounts in naira and ensuring suppliers receive the agreed foreign currency. Customers can also fund their dollar wallets directly with stablecoins, including USDT and USDC, through supported blockchain networks.
Africa’s cross-border payments ecosystem has seen growing stablecoin use for remittances and business settlements. Flutterwave, a Nigerian payments infrastructure company, has begun exploring an integration of USDC settlement into its payments infrastructure. In February, Onafriq partnered with Conduit to use USDC for cross-border payments and payouts to international partners.
“Stablecoins are also part of our settlement infrastructure,” Adedokun explained. “They allow value to move efficiently between parts of the payment stack, but our customers don’t need to understand stablecoins or interact with crypto. They simply know that they were funded in naira and their supplier received dollars, pounds, euros or yuan.”
In August, Clea launched a Vendor Payments feature for businesses that regularly pay the same overseas companies. Adedokun said the product emerged from a deeper understanding of customer needs, shaped by observing how businesses used the platform. Clea serves wholesalers, manufacturers, electronics distributors, fashion businesses, machinery importers and African businesses that depend on international suppliers.
“Initially, we thought speed and FX access were the biggest problems,” he said. “ They are still very important, but once customers started using Clea repeatedly, we realised that trust, payment identity, reconciliation and supplier management are equally important.”
With Vendor Payments, customers can select the supplier from a list of preconfigured vendors whose payment information the platform maintains. They still need to provide the transaction-specific reference the supplier requires, such as a buyer number or lot number, before authorising the payment.
According to Adedokun, Vendor Payments supports US-dollar payments to selected suppliers in the United States, including vehicle auction platforms Copart and IAA.
“If thousands of importers are paying the same shippers, auction companies and suppliers, it doesn’t make sense for every importer to establish that relationship independently every time,” he said. “Once the vendor already exists on Clea, we can simplify the transaction for both sides: fewer incorrect account details, faster reconciliation, better visibility and potentially much faster settlement.”
Clea is betting on importers
Clea makes money primarily from transaction fees and the margin between the exchange rate it sources foreign currency at and the rate it offers customers. Adedokun said the company is building a transaction-driven business, where higher payment volumes and more efficient infrastructure can help lower its underlying costs and improve pricing over time. Since its launch, Clea says it has processed more than $50 million in payments.
“We have to be very disciplined about pricing because our customers understand FX extremely well. These are businesses moving significant amounts of money, so even a small difference in the exchange rate matters,” Adedokun said.
Clea is competing with fintechs such as Verto, Raenest and Grey, which offer businesses multi-currency accounts and international payments. In February, Olayemi Cardoso, Nigeria’s Central Bank (CBN) governor, stated that the country’s average monthly diaspora remittance inflows are about $600 million, showing the scale of cross-border money movement in Nigeria. Adedokun argued that Clea’s focus is narrower: it is building around the specific needs of importers, rather than offering a general-purpose international payments product.
“We don’t think of Clea as another generic international money-transfer product. We are building specifically around the workflow of an importer,” he said. “Our objective is to stay competitive on FX and fees while giving customers speed, reliability, transparency and proper payment documentation.”
When asked about regional expansion, Adedokun said the company is prioritising growth in Nigeria. Its immediate plans include expanding the vendor network, strengthening its payment infrastructure, improving transaction efficiency and reducing the underlying cost of payments.
“There’s a temptation with an African fintech company to announce ten countries very quickly, but there is still a huge amount of market for us to capture in Nigeria,” Adedokun said. “Our immediate priority is to deepen our presence in Nigeria, where we still see considerable opportunities to serve businesses involved in international trade. Ultimately, we want Clea to become the preferred financial infrastructure partner for African businesses trading globally.”